Published on: 7 October 2026
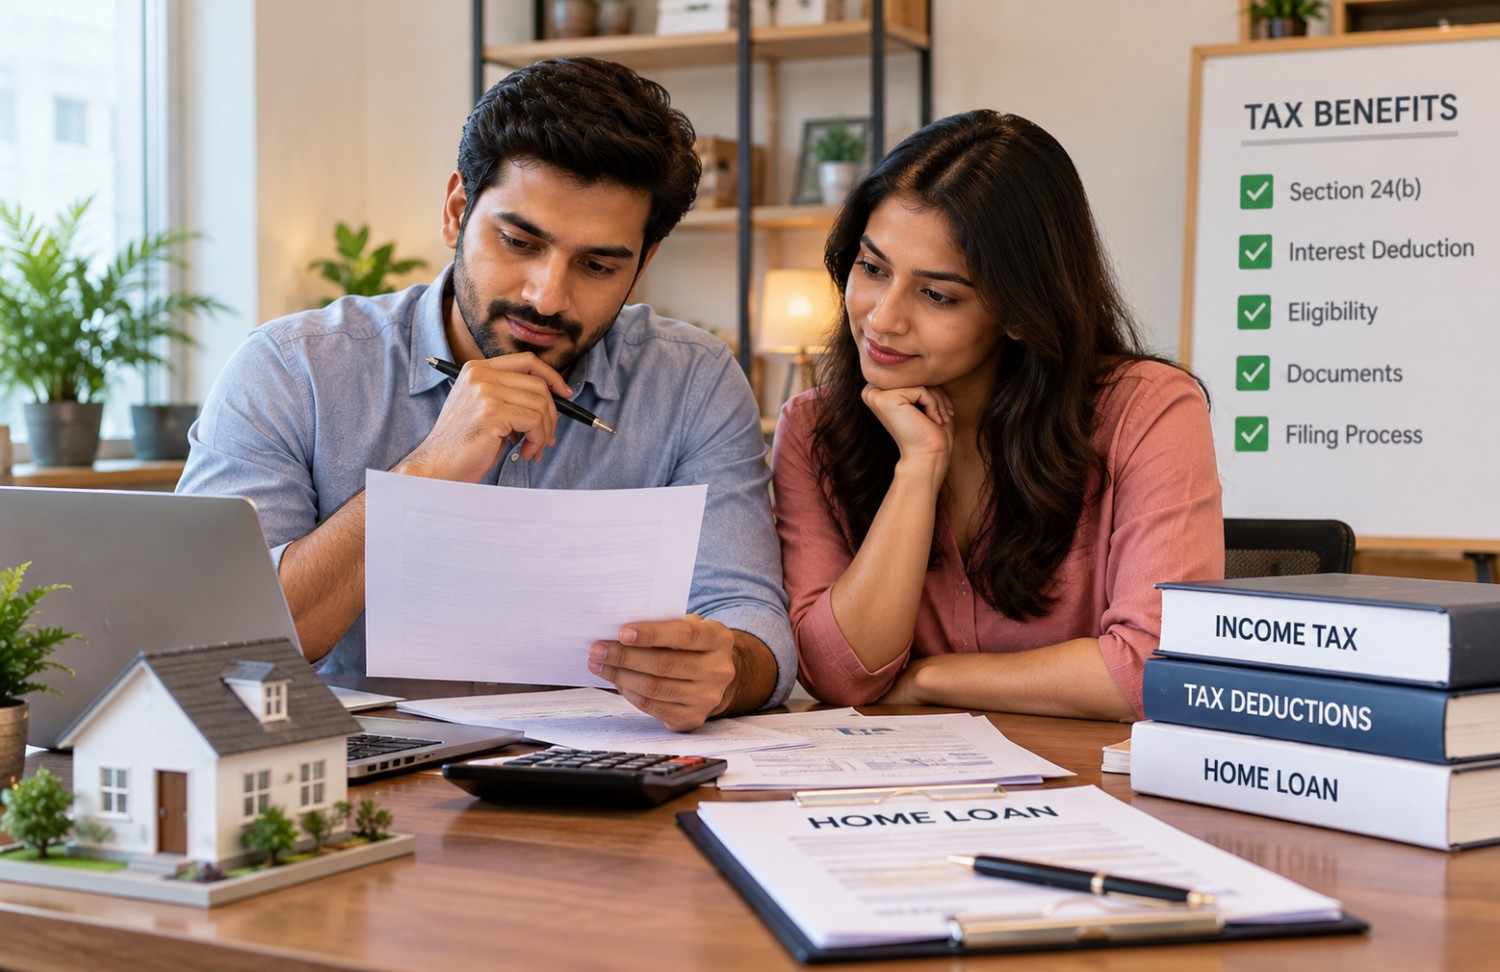
You can claim a tax benefit on a second home loan mainly on the interest paid on the loan. Under the old tax regime, Section 24(b) may allow you to deduct eligible home loan interest from income from house property, subject to applicable rules and limits. If the property is rented, the rental income must also be reported. Keep your loan interest certificate, property documents, rent records and tax receipts to support your claim.
Buying a second home can be an attractive investment strategy, whether you plan to generate rental income, build long-term wealth or eventually use the property yourself. However, taking another home loan also means another financial commitment. Understanding the available tax benefit on second home can help you reduce your taxable income and manage the overall cost of borrowing.
The tax treatment of a second home loan is not exactly the same as that of your first property. Factors such as the property's usage, rental income and the tax regime you choose can affect the deductions available to you. Let's understand how second home loan tax benefits work and how you can claim them correctly.
The tax benefit on second home primarily comes from deductions available on the interest paid on a qualifying home loan. The applicable provisions depend on whether the property is self-occupied or rented and whether you choose the old or new tax regime.
For taxpayers using the old tax regime, Section 24(b) of the Income Tax Act provides for deduction of interest on borrowed capital for a house property, subject to applicable conditions and limits.
A second property that is not self-occupied may be treated as let out or deemed to be let out for income-tax purposes, depending on the circumstances.
One of the most important benefits is the deduction available for interest paid on a housing loan. For a property that is let out, the interest paid on borrowed capital is generally deductible while calculating income from house property. However, the overall treatment of loss from house property and its set-off against other income is subject to applicable limits.
For example, suppose you pay ₹3 lakh as interest on your second home loan during a financial year. If the property is rented out, the eligible interest expense can generally be considered while calculating the taxable income from that property.
Principal repayment of a housing loan can potentially qualify for deduction under Section 80C, subject to the overall Section 80C limit and applicable conditions.
The combined Section 80C limit covers several eligible investments and payments, so you cannot claim an unlimited deduction just because you have paid a large amount toward your second home loan principal.
The way your second property is used can influence its tax treatment.
| Property situation | General tax treatment |
|---|---|
| Self-occupied second property | Special rules apply for determining annual value |
| Rented property | Rental income is taxable after eligible deductions |
| Deemed let-out property | Applicable provisions can require notional rental income to be considered |
| Home loan interest | Deduction may be available under Section 24(b), subject to applicable rules |
If you own multiple residential properties, it is important to understand which property is considered self-occupied and how the remaining property is treated under income-tax rules.
Claiming the deduction is generally straightforward if you maintain the right records.
Ask your bank or housing finance company for an annual home loan interest certificate.
It normally provides details such as:
The interest certificate is particularly useful when preparing your income-tax return.
If your second property is rented, calculate the applicable rental income and eligible deductions according to income-tax rules.
Generally, the calculation considers:
Gross rental income − applicable deductions − eligible home loan interest = taxable income/loss from house property
The exact calculation can vary depending on the circumstances.
For a rented property, eligible municipal taxes actually paid by the owner can be considered while calculating income from house property, subject to applicable conditions.
Keep receipts or other supporting records for these payments.
Maintain documents such as:
These documents can help support your claim if the tax authorities request clarification.
When filing your income-tax return, disclose the relevant house property details and calculate the income or loss according to the applicable provisions.
If you are claiming deductions based on your second property, ensure that the figures match your loan certificate and other supporting documents.
The choice between the old and new tax regimes is important when evaluating your potential tax savings.
The old regime provides access to several deductions and exemptions that may not be available in the same way under the new regime. Therefore, taxpayers with substantial home-loan interest and other deductions should compare their tax liability under both regimes before making a decision.
There is no single answer for every homeowner.
The better option depends on factors such as:
If your second property involves a significant loan, calculate your tax liability under both regimes rather than choosing based solely on the home-loan deduction.
Suppose you purchase a second property and earn ₹4.8 lakh in annual rent.
Assume:
The taxable income from the property would be calculated after considering the applicable deductions and interest expense.
The example is simplified. Actual tax treatment can depend on property ownership, municipal taxes, vacancy, interest, applicable set-off rules and other factors.
Even when you are eligible for a tax benefit on second home, incorrect reporting can reduce the benefit or create compliance issues:
Avoid these mistakes:
For property buyers researching their investment options, resources from platforms such as Search Abode can also help provide broader property-related information, although tax calculations should be based on current income-tax rules.
Before filing your return, keep the following documents available:
You generally do not need to submit every document with your ITR unless specifically required, but retaining them is important for your records.
The tax benefit on second home can make property investment more financially efficient, particularly when the property is financed through a home loan and generates rental income. Interest paid on the loan can play an important role in calculating taxable income from the property, while principal repayment may provide a separate deduction under applicable provisions.
However, second-home taxation can become complicated because the treatment depends on property usage, rental income, loan interest, ownership and your chosen tax regime. Before claiming a deduction, verify the current provisions applicable to your situation and maintain proper documentation. For significant investments, consulting a qualified tax professional can help you calculate the benefit correctly and avoid costly filing mistakes.
The tax saving depends on factors such as your taxable income, loan interest, rental income, eligible deductions and chosen tax regime. There is no fixed tax saving applicable to every second-home owner.
Yes, eligible home loan interest can generally be claimed as a deduction under Section 24(b), subject to applicable income-tax rules. The treatment can differ depending on whether the property is rented, self-occupied or deemed to be let out.
Yes, Section 24(b) can apply to interest paid on a loan taken for a second house, subject to the applicable conditions. The amount you can effectively use against other income may be affected by the rules governing loss from house property.
Principal repayment may qualify for deduction under Section 80C, subject to the overall Section 80C limit and applicable conditions. The availability of this deduction can also depend on the tax regime you choose.
Yes. Rental income from a second property is generally taxable under the Income from House Property head. Eligible deductions, including applicable standard deduction and home loan interest, can reduce the taxable amount.