Published on: 4 July 2026
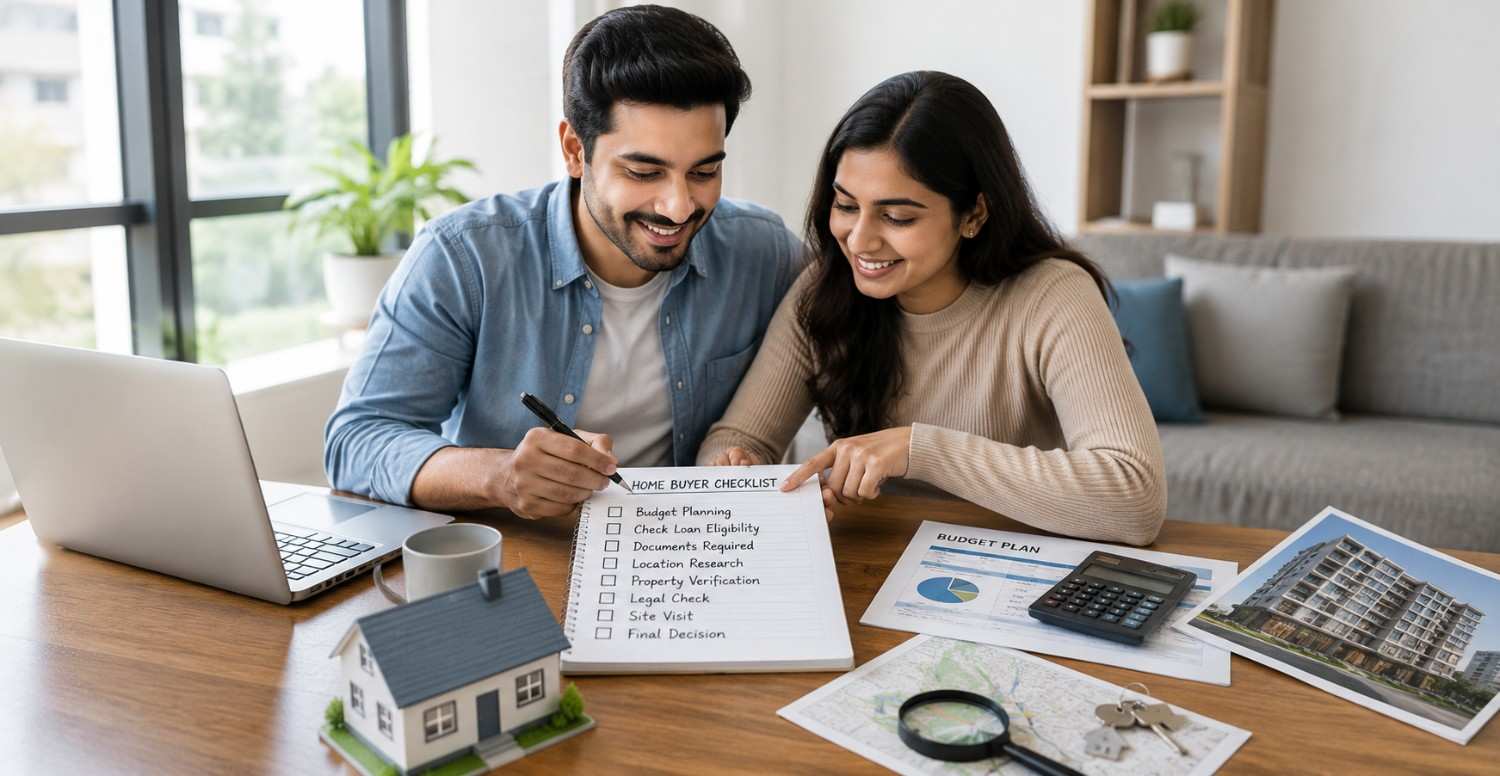
Before buying a property, first-time home buyers should verify their budget, check their credit score, get home loan pre-approval, research the location, verify the builder's reputation, check RERA registration, inspect legal documents, understand hidden costs, physically inspect the property and evaluate future appreciation potential. Following a structured home-buying checklist helps avoid financial and legal issues while ensuring a secure long-term investment.
Would you invest your life's savings without checking all the facts? Buying your first home is not just an emotional decision, it's a major financial investment that requires careful planning, research, and verification. Missing even one important step can lead to unnecessary costs and future complications.
In this guide, you'll discover a complete checklist for first-time home buyers, including budgetin home loans, legal verification, hidden costs, and investment potential. At Search Abode, we help buyers make confident, informed, and future-ready property decisions.
Many home buyers focus only on the property's price and location. However, purchasing a property involves multiple financial, legal, and practical considerations.
A proper home-buying checklist helps you:
Following a structured process can save both time and money.
Before searching for properties, ask yourself why you're buying.
Consider the following questions:
Having clear goals will help narrow down your options and prevent emotional decision-making.
One of the biggest mistakes first-time buyers make is purchasing beyond their financial capacity.
Calculate:
Important costs to include:
| Expense | Approximate Cost |
|---|---|
| Down Payment | 10-25% |
| Stamp Duty | Varies by state |
| Registration Charges | 1-2% |
| Legal Fees | Variable |
| Brokerage | If applicable |
| Maintenance Charges | Variable |
| Interior Expenses | Variable |
Always maintain a financial buffer for unexpected expenses.
Your credit score plays a major role in home loan approval and interest rates.
Ideal credit score:
Before applying for a home loan:
A strong credit profile can save you significant money over the loan tenure.
Getting pre-approved for a home loan provides clarity about your purchasing capacity.
Benefits include:
Documents generally required:
Compare multiple lenders before finalizing your loan.
Location remains one of the most important factors in real estate.
Evaluate:
A good location improves both quality of life and future property appreciation.
If you are purchasing a newly launched or under-construction property, researching the developer is essential.
Check:
At Search Abode, we always recommend verifying a builder's track record before making any investment decisions.
Legal verification is one of the most critical steps in property buying.
Important documents include:
Consult a qualified property lawyer if necessary.
The Real Estate Regulatory Authority (RERA) provides protection to home buyers.
Before purchasing, verify:
Avoid purchasing properties that are not compliant with applicable regulations.
Never rely solely on brochures, advertisements, or online photos.
During the site visit, inspect:
Physical inspection helps identify issues that may not be visible in marketing materials.
Many buyers underestimate the actual cost of property ownership.
Common hidden expenses include:
Understanding these costs prevents budget overruns.
Before signing any agreement, read every clause carefully.
Pay special attention to:
Never sign documents without fully understanding their implications.
A home is not only a place to live but also a long-term investment.
Consider factors such as:
Properties in growth corridors often generate better long-term returns.
Avoid these common errors:
A well-informed buyer is less likely to face future problems.
Buying your first home requires careful planning, research, and due diligence. Taking time to evaluate your finances, verify documents, inspect properties, and understand all associated costs can help you make a confident and informed decision.
Remember, purchasing a property is not just about finding a house,it's about making a secure long-term investment. Whether you're buying your dream home or planning your first real estate investment, following this checklist can help you avoid costly mistakes and make smarter decisions. Search Abode is committed to helping home buyers navigate the property market with confidence and clarity.
First-time home buyers should verify their budget, credit score, home loan eligibility, property documents, RERA registration, builder reputation, hidden costs, and future appreciation potential before making a purchase.
Most lenders require a down payment of around 10% to 25% of the property's value, depending on the loan amount and eligibility criteria.
A credit score of 750 or above is generally considered ideal for securing a home loan at competitive interest rates.
Hidden costs may include stamp duty, registration charges, maintenance deposits, parking fees, brokerage, GST (if applicable), and interior furnishing expenses.
Home loan pre-approval is recommended because it helps determine your budget, improves negotiation power and speeds up the buying process.