Published on: 28 October 2026
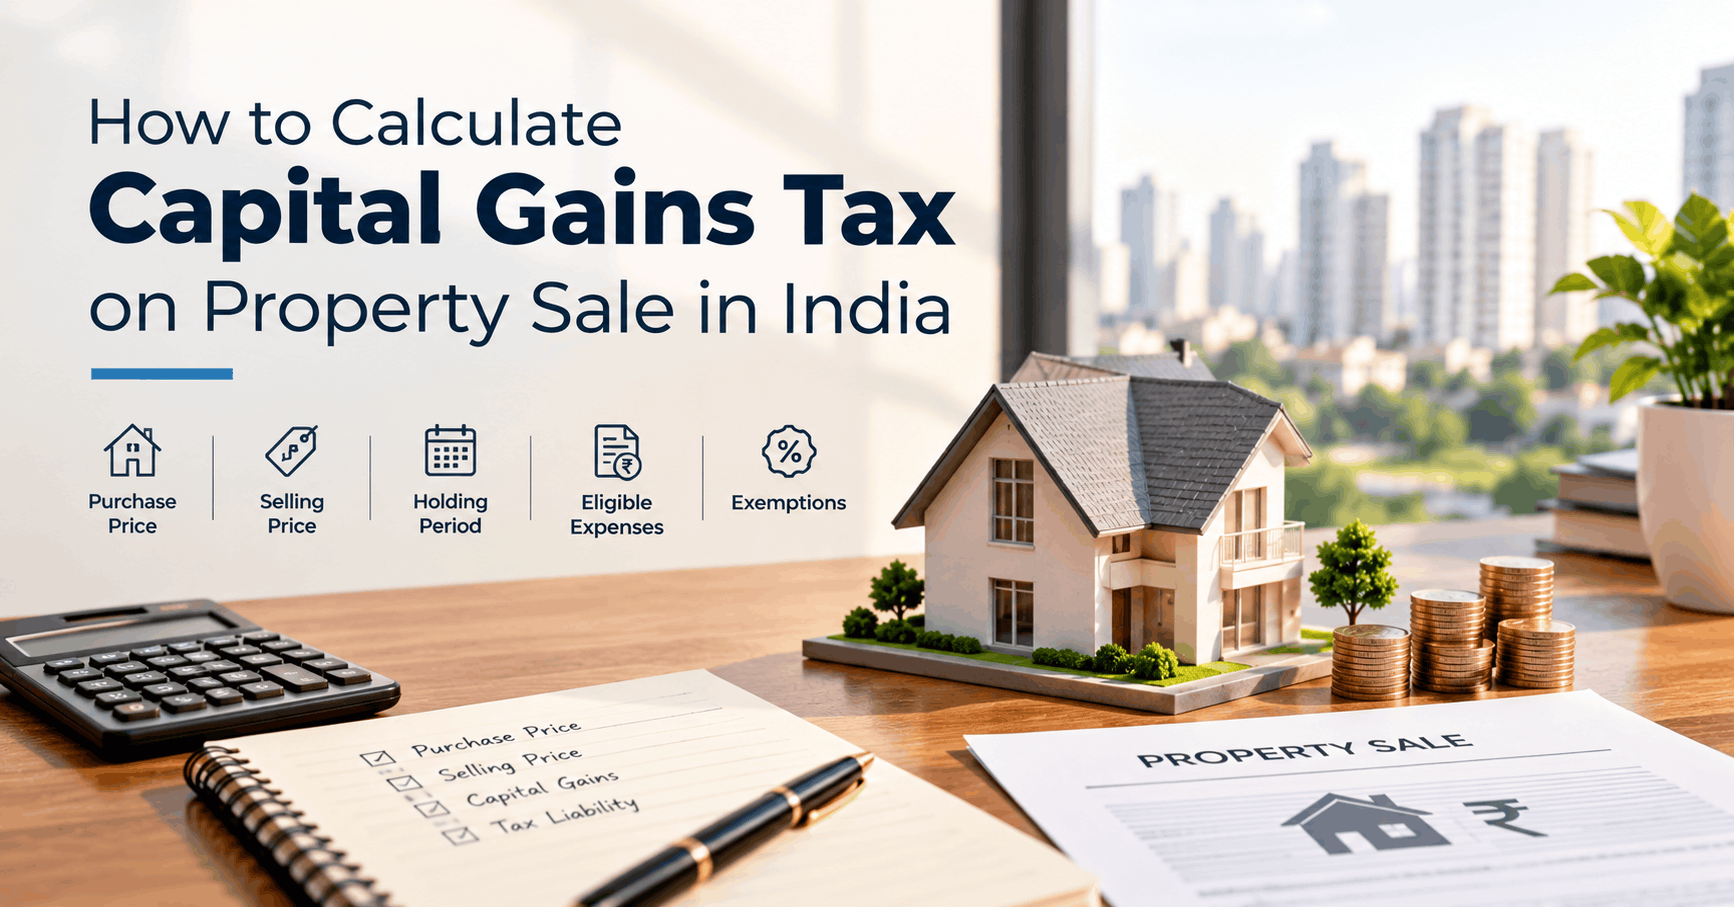
How to Calculate Capital Gains Tax on Property Sale in India
Quick answer
Capital gains tax is generally charged on the profit earned when you sell a property. If you hold land or a building for 24 months or less, the gain is generally classified as short-term and taxed at your applicable income-tax slab rates. If you hold it for more than 24 months, the gain is generally long-term and taxed at 12.5% without indexation for transfers covered by the current rules. Resident individuals and HUFs selling eligible land or buildings acquired before 23 July 2024 may be able to use the older 20% rate with indexation if it results in a lower tax liability. Eligible reinvestments may also reduce or eliminate the taxable gain.
Selling a house, flat, plot or other real estate can result in a profit, but that profit may also create a tax liability. The amount of tax depends on several factors, including the original purchase price, the selling price, the period of ownership, eligible expenses and whether you qualify for an exemption. Understanding these details before finalising a sale can help you plan your finances and avoid unexpected tax payments.
If you are planning to sell a property, understanding capital gains tax on property sale can help you estimate your potential tax liability before completing the transaction. Whether you own a residential flat, an independent house or a plot, reviewing your purchase documents and exploring properties for sale in Jaipur can also help you understand the property market while planning your next investment.
What Is Capital Gains Tax on Property?
Capital gains tax is the tax payable on profit earned from selling a capital asset. When you sell a property for more than its applicable cost, the resulting gain may be taxable under the capital gains provisions of the Income-tax Act.
For example, suppose you purchased a flat for ₹40 lakh and later sold it for ₹65 lakh. The difference is ₹25 lakh before accounting for eligible expenses, improvement costs and other applicable adjustments.
However, the entire difference between the purchase and sale prices is not necessarily taxable. The final calculation depends on the applicable tax rules, the property's holding period, eligible deductions and any exemption you can claim.
Capital gains tax may apply to the sale of:
- Residential flats and apartments
- Independent houses and villas
- Residential and commercial plots
- Commercial buildings and shops
- Other eligible immovable property
The tax treatment can differ if the property is held as business inventory rather than as a capital asset. Properties used for business purposes, inherited assets, jointly owned properties and transactions involving non-resident sellers may also require additional consideration.
Short-Term vs Long-Term Capital Gains on Property
The holding period is one of the most important factors in determining the tax treatment of a property sale.
For land and buildings, the general holding-period threshold is 24 months.
1. Short-Term Capital Gains on Property
If you sell a property after holding it for 24 months or less, the profit is generally treated as short-term capital gain.
Short-term capital gains from ordinary property sales are generally added to your taxable income and taxed at the applicable income-tax slab rates.
For example, suppose you purchase a property for ₹50 lakh and sell it for ₹62 lakh after 18 months. If your eligible transfer expenses and improvement costs total ₹1 lakh, the illustrative gain would be:
- Sale consideration: ₹62 lakh
- Purchase cost: ₹50 lakh
- Eligible expenses: ₹1 lakh
- Short-term capital gain: ₹11 lakh
The ₹11 lakh gain would generally be included in your taxable income and taxed according to the applicable rules and your tax position.
2. Long-Term Capital Gains on Property
If you hold land or a building for more than 24 months before selling it, the gain is generally classified as long-term capital gain.
For transfers covered by the rules effective from 23 July 2024, the standard long-term capital gains rate is 12.5% without indexation. Certain resident individuals and Hindu Undivided Families (HUFs) can use a special comparison for eligible land or buildings acquired before 23 July 2024.
For example, if you purchased a flat for ₹45 lakh and sold it for ₹80 lakh, the gain before eligible adjustments would be ₹35 lakh.
The final taxable amount may be lower after deducting eligible transfer expenses and improvement costs. Any available exemption must also be evaluated separately.
How to Calculate Capital Gains Tax on Property Sale
The basic calculation starts with the property's sale value and subtracts the costs permitted under the applicable tax rules.
Step 1: Determine the Sale Consideration
Start with the amount received or receivable from the property sale. Also check the stamp duty value because special tax rules may apply when the declared sale price is lower than the stamp duty value.
Under the applicable deemed-consideration rules, the stamp duty value may be substituted for the actual sale price in certain circumstances. A tolerance rule can apply where the stamp duty value does not exceed 110% of the actual consideration, subject to the applicable conditions.
Step 2: Deduct the Cost of Acquisition
The cost of acquisition is generally the amount paid to acquire the property, adjusted as required by the tax rules.
For inherited or gifted property, special rules may apply to determine the cost and holding period. In many such cases, the previous owner's cost and ownership period become relevant.
Step 3: Deduct Eligible Improvement Costs
Certain capital expenses incurred to improve the property may be deductible when calculating the gain. Keep invoices and supporting documents for qualifying construction, renovation or improvement expenses.
Routine maintenance and ordinary repairs do not automatically qualify as capital improvement costs. The treatment depends on the nature of the expenditure and the applicable provisions.
Step 4: Deduct Eligible Transfer Expenses
Expenses incurred wholly and exclusively in connection with the sale may be deductible. Depending on the circumstances, these may include qualifying brokerage or legal expenses directly related to the transfer.
Keep appropriate bills, agreements and payment records to support any deduction claimed.
Step 5: Calculate the Capital Gain
The basic formula is:
Capital Gain = Applicable Sale Consideration − Eligible Transfer Expenses − Cost of Acquisition − Eligible Cost of Improvement
For long-term gains, the applicable rules determine whether original costs or indexed costs are used. The final tax calculation must also account for any eligible exemption and applicable tax rate.
Example: Property Sale Tax Calculation
Suppose you purchased a residential property for ₹50 lakh and sold it for ₹85 lakh. Assume you paid ₹2 lakh in eligible transfer expenses and incurred ₹3 lakh in qualifying improvement costs.
| Particulars | Amount |
|---|---|
| Sale consideration | ₹85,00,000 |
| Less: Purchase cost | ₹50,00,000 |
| Less: Eligible transfer expenses | ₹2,00,000 |
| Less: Eligible improvement costs | ₹3,00,000 |
| Illustrative capital gain | ₹30,00,000 |
If the gain qualifies as long-term and the standard 12.5% rate applies without indexation, the illustrative base tax would be ₹3,75,000 before any eligible exemption, surcharge or cess.
This is only an example. The actual tax may differ depending on the acquisition date, transfer date, stamp duty value, applicable tax regime and exemption eligibility.
What Is Indexation in Property Capital Gains?
Indexation adjusts an eligible property's cost to account for inflation using the Cost Inflation Index (CII). Under the older tax framework, it helped reduce the taxable gain by increasing the property's indexed cost.
For transfers on or after 23 July 2024, the general rule for long-term capital gains changed to a 12.5% rate without indexation.
However, a special relief applies to certain properties acquired before 23 July 2024. A resident individual or HUF selling eligible land or a building may compare:
- Tax calculated at 12.5% without indexation under the new rules.
- Tax calculated at 20% using indexation under the earlier method.
Where the statutory conditions are satisfied, the tax payable under the new method cannot exceed the tax calculated under the earlier method for the eligible property.
This comparison is not available to every taxpayer or every property. It is important to confirm the acquisition date, ownership status and transfer details before choosing the more beneficial calculation.
Capital Gains Exemption on Property Sale
The tax law provides certain exemptions when eligible capital gains or sale proceeds are reinvested in specified assets. The conditions, deadlines and investment limits depend on the exemption being claimed.
1. Reinvesting in Another Residential House
Under the familiar Section 54 framework, an eligible individual or HUF selling a residential house and earning long-term capital gains may claim relief by purchasing or constructing another residential house in India.
The general time limits are:
- Purchase a new residential house within one year before the sale or within two years after the sale.
- Construct a new residential house within three years after the sale.
The exemption is subject to the applicable conditions and statutory limits. Under the current framework, the qualifying investment and the amount of capital gain eligible for relief must be calculated carefully.
This option may be useful for homeowners who plan to sell their existing house and purchase another home.
2. Selling a Long-Term Asset and Purchasing a Residential House
Under the familiar Section 54F framework, an eligible individual or HUF selling a long-term capital asset other than a residential house may qualify for relief by investing the net sale consideration in a residential house, subject to the relevant conditions.
This exemption can have different requirements from the exemption available when selling an existing residential house. In particular, ownership of other residential properties and the amount reinvested may affect eligibility.
3. Investing in Specified Bonds
Eligible long-term capital gains from the transfer of land or buildings may qualify for relief when invested in specified bonds issued by eligible institutions, subject to the applicable statutory conditions.
The familiar Section 54EC framework generally provides a six-month investment window from the date of transfer and a maximum eligible investment of ₹50 lakh. The bonds are subject to a prescribed lock-in period and other conditions.
Confirm the eligible bond type, investment deadline and applicable rules before relying on this option.
4. Depositing Unused Amounts Under the Capital Gains Account Scheme
Sometimes, the property sale proceeds or capital gains cannot be reinvested before the income-tax return filing deadline. Eligible taxpayers may be able to deposit the required amount into a Capital Gains Account Scheme account within the prescribed time to preserve a potential exemption.
The deposit must satisfy the applicable rules, and the money must be used for the qualifying purpose within the specified period. An unused balance may become taxable under the relevant provisions.
Important: The Income-tax Act, 2025 came into force on 1 April 2026 and reorganised the tax framework. The familiar section numbers above are commonly used in older guidance. For a transaction under the new Act, verify the corresponding current provisions, eligibility and forms before claiming an exemption.
Documents Required to Calculate Property Capital Gains
Keeping accurate documents makes it easier to calculate the gain and support any deduction or exemption claimed.
Commonly useful documents include:
- Original purchase agreement and payment records
- Sale agreement and transfer documents
- Stamp duty and registration records
- Invoices for eligible improvement work
- Brokerage and other qualifying transfer-expense receipts
- Inheritance or gift documents, where applicable
- Proof of eligible reinvestment in a new residential property
- Specified bond investment receipts, if claiming that relief
- Capital Gains Account Scheme deposit records, where applicable
- Previous owner's acquisition records when relevant
The exact documents depend on the property's ownership history and the tax treatment being claimed. Keep records of the dates and amounts of payments, as these may affect the calculation.
Common Mistakes to Avoid When Calculating Capital Gains
Ignoring the Holding Period
The difference between short-term and long-term treatment can significantly affect the tax calculation. Check the relevant acquisition and transfer dates before estimating tax.
Using the Sale Price Without Checking Stamp Duty Value
The tax law may require a different deemed sale value in certain cases. Check the applicable stamp duty valuation rules before calculating the gain.
Assuming Indexation Is Available for Every Property
The general long-term rule changed for transfers on or after 23 July 2024. The special comparison for certain older properties is limited to eligible resident individuals and HUFs.
Claiming Expenses Without Supporting Documents
Not every expense qualifies as a deduction. Maintain invoices and proof of payment for expenses claimed in the calculation.
Missing Reinvestment Deadlines
Exemptions may depend on strict purchase, construction or investment deadlines. Plan the reinvestment before the sale is completed and verify the applicable conditions.
Assuming the Entire Gain Can Always Be Exempted
Some exemptions depend on the amount reinvested, the type of asset sold, ownership conditions and statutory limits. Calculate the eligible exemption rather than assuming the whole gain will be tax-free.
Conclusion
Calculating capital gains tax on property sale requires more than subtracting the original purchase price from the selling price. The holding period, eligible expenses, stamp duty value, applicable tax rate and potential exemptions all affect the final liability. Reviewing these details before selling can help property owners estimate their tax obligations and plan their next financial step.
If you are selling a property and planning to purchase another home, compare your reinvestment options and review flats for sale in Jaipur alongside your budget and timeline. Since tax rules depend on individual circumstances and the transaction date, consult a qualified tax professional before filing your return or making an investment to claim an exemption.
Frequently Asked Questions
Start with the applicable sale consideration and deduct eligible transfer expenses, acquisition cost and qualifying improvement costs. Apply the relevant short-term or long-term tax rules, then account for any eligible exemption.
For land and buildings, the general threshold is more than 24 months. A property held for 24 months or less is generally treated as a short-term capital asset.
For eligible transfers covered by the rules effective from 23 July 2024, the standard rate is 12.5% without indexation. Certain resident individuals and HUFs may qualify for the special comparison for eligible land or buildings acquired before that date.
Short-term capital gains from ordinary property sales are generally included in taxable income and taxed at the applicable income-tax slab rates.
You may qualify for an exemption if you meet the conditions for reinvesting in a qualifying residential house. The permitted time limits, investment requirements and ownership conditions depend on the relevant provision.
Indexation is generally not available for long-term property transfers covered by the rules effective from 23 July 2024. Eligible resident individuals and HUFs selling certain properties acquired before that date may be able to compare the 20% indexed method with the 12.5% method without indexation.